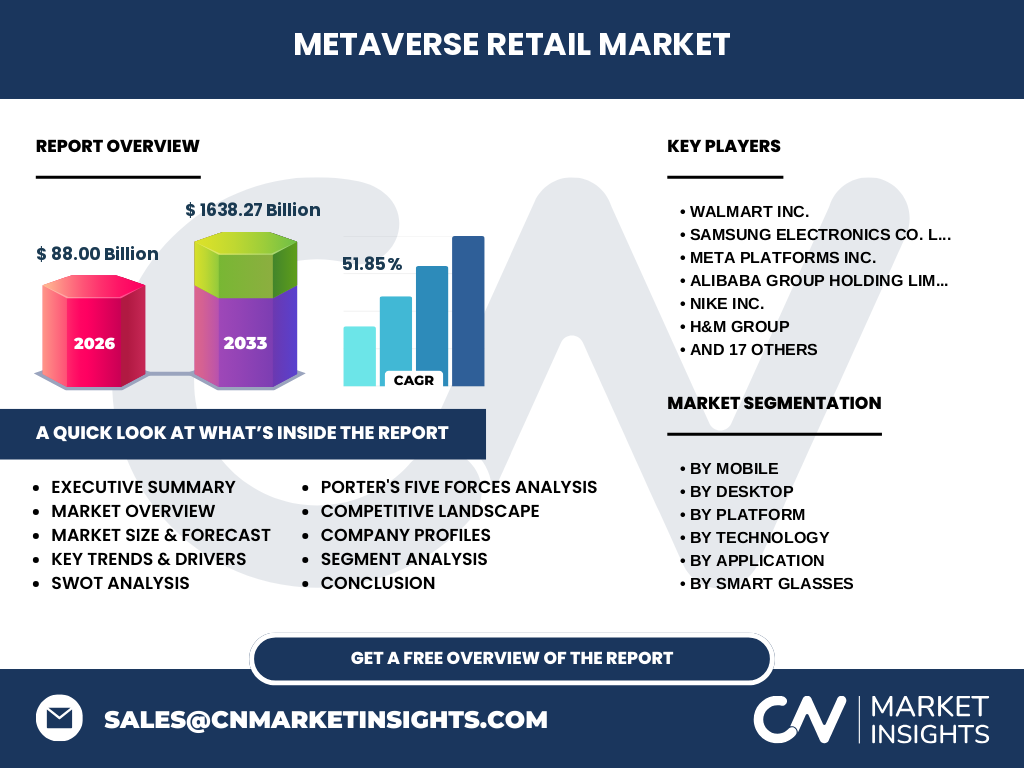
Market Overview: Defining the Metaverse Retail Market Scope
The Metaverse Retail Market represents the convergence of immersive digital environments and transactional commerce. Valued at 88.00 Billion in 2026, this sector encompasses virtual storefronts, phygital goods, and social shopping experiences. It transcends traditional e-commerce by integrating Blockchain and AI to create persistent, interconnected economic spaces where consumers interact with brands through VR Headsets or mobile interfaces, fundamentally reshaping global consumer behavior patterns.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the 51.85% CAGR, driven by mainstream adoption of Augmented Reality (AR) and Cloud Computing. Conversely, the market faces significant logistical hurdles, including interoperability challenges across platforms like Decentraland and The Sandbox. Furthermore, regulatory scrutiny regarding digital asset ownership and data privacy remains a critical constraint, necessitating robust legal frameworks to secure consumer trust in virtual transactions.
Emerging Trends and Strategic Patterns
We observe a paradigm shift toward 'phygital' commerce, where brands like Nike and Adidas link physical product ownership to exclusive digital assets. The trend toward Virtual Try-On technology, powered by sophisticated AI algorithms, is reducing return rates significantly. Moreover, the rise of Digital Product Commerce is allowing retailers to bypass supply chain constraints, enabling high-margin sales of virtual-only goods that require no physical warehousing.
COVID-19 Impact and Recovery Trajectory
The pandemic served as a catalyst for digital transformation, forcing brick-and-mortar giants to accelerate their Metaverse Retail Market presence. Post-COVID recovery has been characterized by a permanent shift in consumer expectations toward seamless omnichannel engagement. Firms that invested early in mobile and web-based platforms during the lockdown have successfully transitioned into dominant players, leveraging virtual storefronts to maintain customer engagement during physical mobility restrictions.
Competitive Benchmarking and Strategic Dynamics
The landscape is dominated by tech titans and lifestyle innovators. Meta Platforms and Roblox control the infrastructure, while luxury houses like Guccio Gucci and Balenciaga utilize virtual marketplaces to engage younger demographics. Market concentration remains high among early movers, though Immutable Pty Ltd. and OpenSea are democratizing access to digital product commerce, creating a fierce rivalry between proprietary closed-ecosystems and open, blockchain-based decentralized platforms.
Executive Summary: Synthesis of Findings
The Metaverse Retail Market is poised for exponential growth, projected to reach 1638.27 Billion by 2033. Our research identifies AI and AR as the core technological pillars driving this expansion. Success hinges on bridging the gap between immersive marketing and practical utility, where platforms like ZEPETO successfully synthesize social shopping with revenue generation, presenting a massive ROI opportunity for global retail stakeholders.
Market Forecast: Projections from 2027 to 2033
Between 2027 and 2033, the market will experience a rapid compounded growth rate of 51.85%. This trajectory reflects the transition from niche experimentation to widespread enterprise adoption. As hardware constraints lessen—specifically regarding the cost and weight of Smart Glasses—we anticipate a surge in consumer daily usage, pushing the total valuation from a 2026 baseline of 88.00 Billion to 1638.27 Billion by the end of our forecast period.
Segmentation Analysis: Core Components
Our analysis categorizes the market into: Technology (Blockchain, AI, AR/VR), Platform (Mobile, Desktop, VR Headsets), and Retail Activity. Segmenting by Virtual Storefronts and Digital Product Commerce allows for granular visibility into revenue streams. Specifically, the Mobile segment—spanning Android, iOS, and Cross-Platform applications—remains the most critical volume driver due to its immediate accessibility for the global mass market compared to specialized Tethered VR Headsets.
Regional Market Performance and Distribution
Performance varies significantly by infrastructure maturity. North America leads in innovation and investment, driven by Meta and Roblox. Asia-Pacific, anchored by Alibaba and ZEPETO, shows the highest adoption of social shopping and mobile-integrated virtual platforms. Meanwhile, Europe focuses on regulatory alignment regarding digital commerce, impacting the rollout of virtual showrooms. These regions represent distinct strategic clusters that require localized penetration tactics to achieve maximum market share.
In-Depth Regional Review
In North America, the market is characterized by high consumer spending on fashion and apparel virtual goods. In contrast, the Asia-Pacific region excels in mobile-based retail integration, leveraging mature digital payment ecosystems. Samsung Electronics and Alibaba are key drivers here, emphasizing hyper-localized virtual events that mirror the shopping habits of local urban centers, confirming that regional nuances dictate the success of any global Metaverse retail strategy.
Strategic Positioning of Leading Companies
Companies like Walmart focus on logistical integration of virtual retail with physical delivery, while Louis Vuitton and Ralph Lauren prioritize brand equity through exclusive digital luxury collections. Spatial Systems and VRChat provide the immersive environments necessary for these brands to flourish. This strategic grouping allows firms to either act as infrastructure providers or content creators, each occupying distinct segments of the growing digital value chain.
Porter's Five Forces: Competitive Forces Assessment
The threat of new entrants is moderate due to high capital requirements for AR/VR and Blockchain infrastructure. Buyer power is high as consumers demand cross-platform interoperability. Rivalry among existing giants like Epic Games and Meta is intense, centered on attracting user attention. Supplier power is concentrated in semiconductor and hardware manufacturers, while the threat of substitutes remains limited, as virtual retail creates unique value propositions unreachable through traditional e-commerce.
SWOT Analysis of the Market
Strengths include high engagement rates and massive scalability. Weaknesses persist in hardware adoption and user latency issues. Opportunities abound in phygital goods and AI-driven personalization, while threats include fragmented regulatory compliance across jurisdictions and potential cybersecurity risks. Successfully navigating these factors requires a balanced strategy that addresses both technological hardware limitations and the critical need for seamless, intuitive user experiences across all virtual platforms.
Value Chain Analysis: Flow from Infrastructure to Users
The value chain originates with hardware manufacturers (e.g., VR Headsets, Smart Glasses), flows through cloud computing providers, and reaches platform developers. Finally, retailers like Nike and H&M create the content. Value is added at each step through AI integration and blockchain verification, ensuring secure ownership of digital assets. This flow concludes with the end-user, who engages via mobile or desktop to complete transactions.
Strategic Investment Insights and Opportunities
We recommend focusing investments on interoperable platforms and AI-driven virtual try-on software. These high-potential areas bridge the current gaps between disparate virtual worlds. Furthermore, the phygital goods sector remains an untapped goldmine, allowing retailers to monetize both physical and digital inventories simultaneously. Investors should prioritize firms that are building open-standard ecosystems rather than isolated 'walled gardens,' as these will likely capture the largest share of the 1638.27 Billion market forecast.
Conclusion and Key Takeaways
The Metaverse Retail Market is fundamentally transforming how brands connect with consumers. With a projected 51.85% CAGR, stakeholders must shift focus from experimental marketing to operationalized virtual commerce. Key success factors include investing in AI-driven personalization, ensuring multi-platform accessibility, and navigating the evolving regulatory landscape. Those who prioritize these strategic pillars will lead the next generation of retail, transforming digital presence into tangible, sustained global revenue growth.
Research Methodology: How Baseline Data is Triangulated
Our research methodology employs data triangulation by merging trade registry analysis, in-depth primary stakeholder interviews, and secondary macroeconomic indicators. We systematically cross-reference company announcements from players like The Sandbox and Voxels with real-time transaction volume data. This rigorous process ensures that our 2026 baseline of 88.00 Billion and our 2033 forecast are grounded in factual, observable market performance, providing a reliable and defensible perspective for institutional investment and strategic planning.
Scope of the Report: Parameters and Limitations
This report covers the global Metaverse Retail Market, specifically evaluating Hardware, Software, and Service segments. The study spans 2026 to 2033, focusing on major retail applications including Beauty, Electronics, and Apparel. Limitations include the rapid evolution of regulatory standards and potential volatility in cryptographic asset valuations. We exclude non-retail metaverse applications like enterprise-only collaboration tools to maintain focus on consumer-facing retail and commercial transaction systems.
Recent Developments in the Industry
Recent strategic moves include Nike's deepening integration of NFT-linked apparel and Adidas's aggressive expansion into virtual collaborative events. Additionally, platforms like Spatial Systems have recently announced cross-platform upgrades for Smart Glasses, while DRESSX continues to lead in digital-only clothing. These announcements signal a clear shift toward higher fidelity, interactive, and socially-driven retail experiences, underscoring the industry's rapid maturity since our last research cycle began.